You can build a strong portfolio, pay your SIPs on time and still leave your family in a mess. Not because you did anything wrong with money, but because the paperwork was never done. Wealth is not only what you earn and invest. It is also what actually reaches the people you love, quickly and without a fight. These six documents decide that. Most families have one or two of them. Very few have all six, and even fewer have kept them up to date. Here is what each one does, what happens without it, and what to do this month.
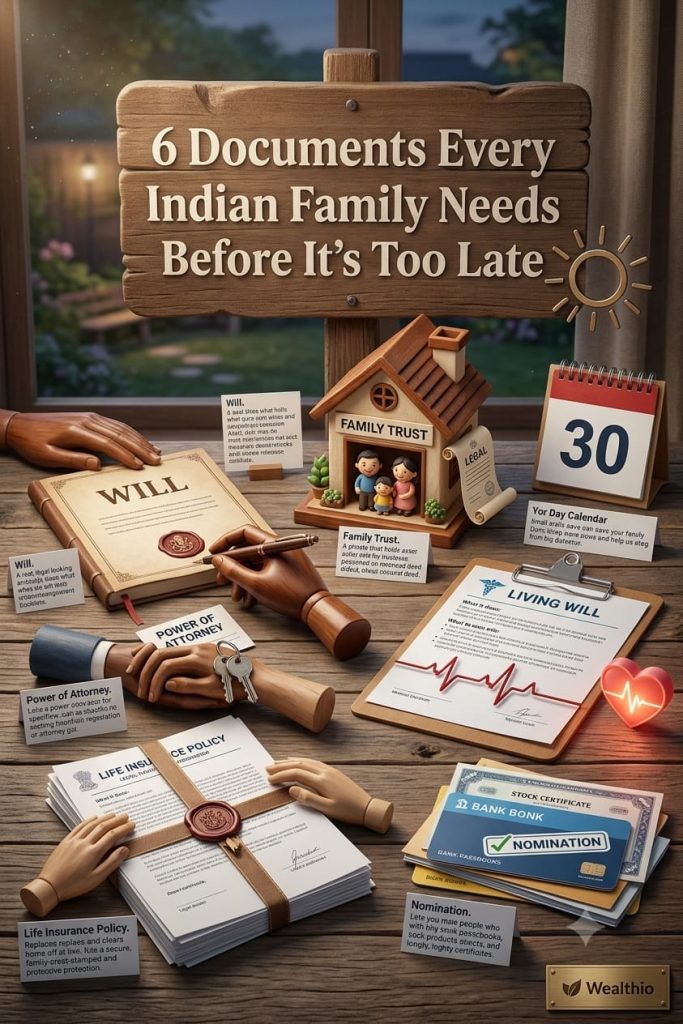
1. Will: Your Instructions, in Your Words
What it does: A will states who gets what. It also names an executor, the person who carries out your wishes.
What happens without it: If you die without a will, your property passes under the succession law of your religion, such as the Hindu Succession Act or the Indian Succession Act. That may not match what you wanted, and your family may need a legal heir or succession certificate before banks and other institutions release anything.
The hidden risk: A will that cannot be found is as good as no will. If the signed original is lost, your family may have to prove its contents in court or fall back on intestate succession.
What to do:
* Write a clear will, ideally with legal help, and sign it in front of two witnesses.
*Consider registering it. Registration is optional in India, but it makes tampering and later disputes harder.
* Tell your executor where the original is kept. A bank locker or a fireproof file at home both work, as long as someone knows.
* Review it after any major life event: marriage, a child, a new property, a death in the family.
Good to know: In some cities and situations, a will must go through probate (a court process that validates it) before it can be acted on. Ask an advocate whether this applies to your family.
2. Family Trust: For Assets You Want to Pass On Smoothly
What it does: A private trust holds assets for your beneficiaries under rules you set. Assets placed in the trust are managed by trustees and passed on according to the trust deed, without waiting for the usual succession process.
What happens without it: Property that is only in your name, such as a house, land or a business stake, can be tied up while your heirs establish their right to it. If there are several heirs, or a dependent who needs long-term support, this gets harder.
Who should think about it: Families with multiple properties, a business, children who are minors, or a family member with special needs. A trust is not for everyone. It has setup costs and needs careful drafting, so speak to a lawyer and a tax advisor before deciding.
3. Power of Attorney: Know Its Limits
What it does: A Power of Attorney (POA) lets a person you trust act for you on specific matters, such as signing documents, handling a property registration or operating a bank account while you are abroad or unable to travel.
The limit most people miss: In India, a POA generally ends when the person who granted it dies, and it is generally treated as ending if that person becomes of unsound mind. That means it is not a complete plan for the day you can no longer manage your own affairs. The foreign concept of a “durable” POA that survives incapacity does not work the same way here.
What to do:
* Use a POA for practical, defined tasks, and keep its scope narrow and in writing.
* Do not rely on it as your only plan for incapacity. Joint accounts with a trusted person, proper nominations and a family conversation matter just as much.
* Ask a lawyer how to prepare for incapacity in your specific situation.
4. Living Will: Your Medical Wishes, in Writing
What it does: A living will, legally called an Advance Medical Directive, records the medical treatment you do or do not want if you are terminally ill or permanently unable to communicate. It can also name the person who should make decisions for you.
Is it legal in India? Yes. The Supreme Court recognised living wills in its 2018 Common Cause judgment, and in January 2023 it simplified the process. Today the document is signed in front of two witnesses and attested by a notary or a gazetted officer, and a copy should be given to your family physician.
An honest note: Implementation on the ground is still patchy, and many hospitals and families are unsure how to act on these documents. That is exactly why you should talk to your family and your doctor in advance, not just file the paper away.
What to do:
* Draft the directive using the format prescribed in the Supreme Court guidelines, and get it attested.
* Name the person who should speak for you.
* Give copies to that person, your family and your physician.
5. Life Insurance Policy: Only Useful If Your Family Can Find It
What it does: It replaces income and clears debts like a home loan if the earning member is no longer there.
What happens without it, or when no one knows about it: A policy that your family does not know exists may never be claimed. The money sits with the insurer while your family struggles.
What to do:
* Keep a simple list of every policy: insurer, policy number, sum assured, premium due date, and the nominee.
* Keep premiums paid. A lapsed policy pays nothing.
*Tell at least one trusted family member where the policy documents are, and consider holding your policies in an electronic insurance account so they are all in one place.
*Check that your cover is still enough for your current income, loans and dependents.
6. Nominee Details: The Update Everyone Forgets
What it does: A nominee is the person named on your bank account, fixed deposit, insurance policy, mutual fund folio, demat account or EPF to receive the money after your death.
The mistake: Outdated nominees. An ex-spouse, a parent who has passed away, or a blank nomination form that was never filled in can all delay or complicate a claim.
The distinction that matters: In many cases, a nominee is the person who receives the money, but does not automatically become its owner. Legal heirs may still have a claim under your will or under succession law, and a nominee who ignores that can be asked to account for it. If your will and your nominations disagree, you are inviting a family dispute. Make them consistent.
Good news on banks: Since 1 November 2025, you can name up to four nominees on bank deposits and lockers, either with set percentage shares or in a sequence (successive nomination). Check the current nominee limits and rules for your mutual funds and demat accounts too, since these have been revised recently.
What to do this month:
* List every account and investment you hold, and check who is nominated on each.
* Update outdated nominees. Add nominees where there are none.
* Make sure your nominations match your will.
Your 30-Day Family Paperwork Plan
* Week 1: List every asset and liability: bank accounts, FDs, mutual funds, demat, EPF/PPF, insurance, property, loans.
* Week 2: Check and update every nominee.
* Week 3: Draft your will, and decide whether you need a trust, a POA or a living will.
* Week 4: Put copies in a labelled folder, and tell one trusted person where everything is.
A simple tip: keep a one-page “If something happens to me” sheet with the names of your advocate, CA, insurance agent and key contacts, and where the documents are stored.
The Bottom Line
These six documents are not about death. They are about making sure your family stays financially and emotionally safe when life is already hard. Spend a weekend on this now, and you save your family months of running between banks, courts and offices later.
Build the routine. Build the wealth. And protect the people it is meant for.
Disclaimer: This article is for general education and is not legal, tax or financial advice. Succession, trust and tax rules depend on your religion, state and circumstances, and they change. Please consult a qualified advocate and a financial advisor before acting.
-Admin, Wealthio