Every person has 24 hours in a day. Yet, over time, people can arrive at very different financial destinations. Some gradually build savings, acquire assets, develop valuable skills, and create financial security. Others work hard for years but struggle to move beyond their monthly expenses. One important factor is the collection of small decisions we repeat every day. The way we manage money, use our time, respond to opportunities, and prepare for the future can influence our financial journey far more than we realise.
However, wealth is not determined by habits alone. Family background, income, education, health, economic conditions, and access to opportunities also matter. The real lesson is not to judge people by their financial position, but to recognise the habits and systems that can help us make better use of the resources available to us.
Rich Habits Begin with a Different Mindset. People who build lasting wealth tend to think beyond immediate satisfaction. This difference in perspective influences everyday choices. A wealth-building mindset focuses on progress rather than appearances, financial independence rather than social comparison, and long-term security rather than temporary excitement. Before making an important financial decision, consider both its immediate benefit and its long-term consequences.
They Use Time to Build Skills and Opportunities. Time is one of our most valuable resources because, once spent, it cannot be recovered. People who improve their financial position often invest some of their available time in learning, developing professional skills, understanding their industry, building useful relationships, or exploring new income opportunities. This does not mean every free minute must be productive. Rest, recreation, and time with family are essential. The issue is whether our daily routine leaves room for personal and professional growth. Reading about money, learning technology, improving communication, and understanding business fundamentals can all contribute to better decisions. Learning something that can improve your knowledge, career, business, or financial decisions.
They Make Saving a Habit, Not an Afterthought. One of the most common financial mistakes is following the rule: earn money, spend it, and save whatever remains. Unfortunately, very little may remain at the end of the month. A more effective approach is to plan savings alongside essential expenses. Even a small, consistent amount can help establish financial discipline. The purpose is not to impose the same savings target on everyone. Someone supporting a large family on a limited income may have very little room to save. In such cases, improving income, controlling avoidable expenses, and building even a small emergency reserve may be more realistic first steps. Decide on a realistic savings amount, set it aside regularly, and increase it when your financial circumstances allow.
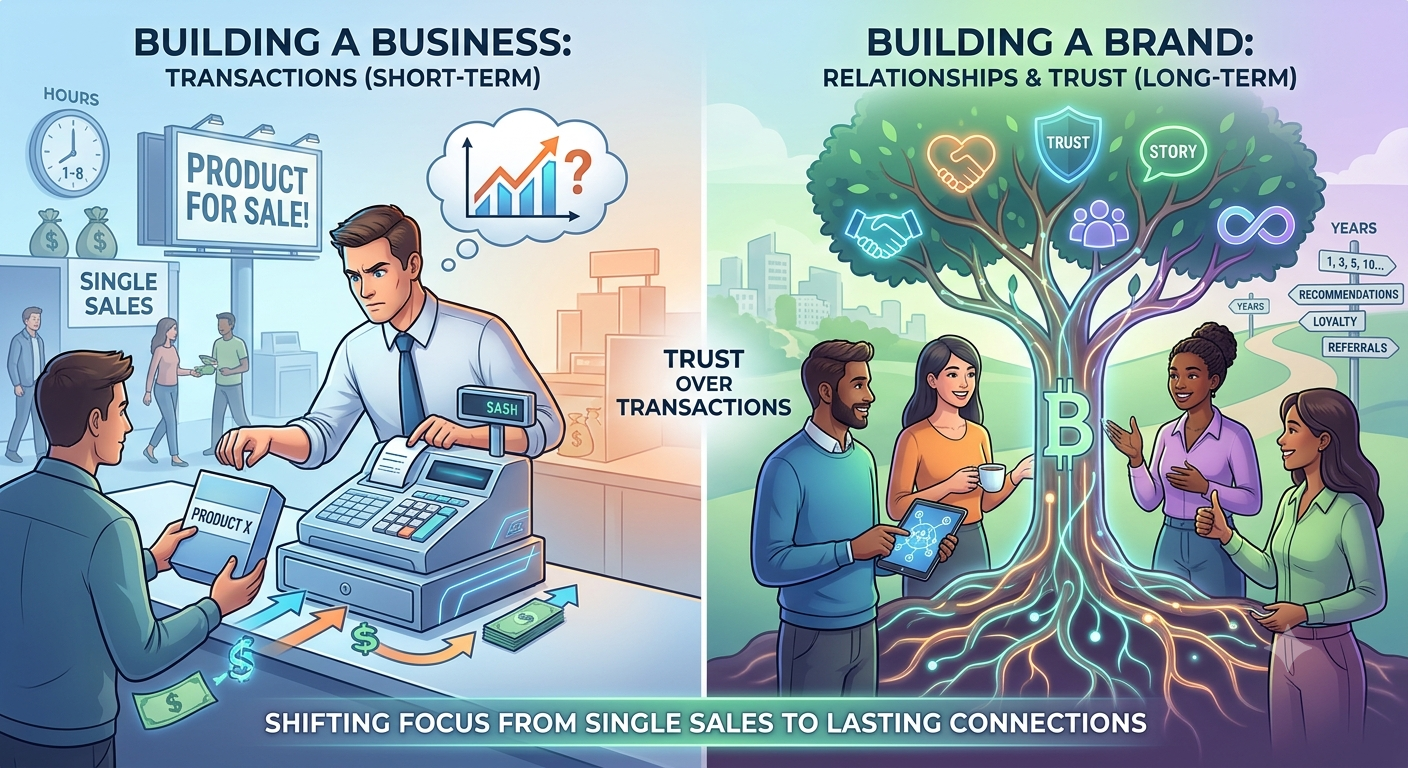
They Understand the Difference Between Assets and Liabilities. Earning money and building wealth are two different achievements. Income is the money we receive. Wealth is what we accumulate after accounting for what we owe. A person may earn a high salary but have little financial security because most of the income goes towards an expensive lifestyle, loan repayments, and other obligations. Another person with a moderate income may gradually build wealth by controlling expenses, reducing costly debt, and acquiring suitable assets. Wealth-building habits include understanding the purpose of every major purchase, reviewing debt obligations, maintaining savings, and investing according to personal goals and risk tolerance. The important question is whether a financial decision supports your needs and long-term plan. Review your assets, liabilities, savings, and financial commitments regularly instead of judging your financial success by income or possessions alone.
They Think Long Term and Respect the Power of Compounding. Wealth is rarely created through one perfect decision. More often, it grows through repeated, sensible decisions over many years. Compounding occurs when investment returns remain invested and can themselves generate further returns. Over long periods, this process can significantly increase the value of an investment.
However, compounding requires time, consistency, and patience. Returns are not guaranteed, and investments carry different levels of risk. The objective should not be to chase the highest possible return. It should be to build a financial plan that can withstand uncertainty while supporting future goals. Give your financial goals a timeline, review your investments periodically, and avoid abandoning a sound plan simply because of short-term market movements. They Protect Their Health and Build Strong Relationships. Financial success is not created by money management alone. Poor health can interrupt earning capacity and create unexpected expenses. Continuous stress, inadequate sleep, and an unhealthy routine can also make it harder to concentrate and make considered decisions. Similarly, supportive relationships can provide encouragement, knowledge, professional opportunities, and emotional stability. Learning from experienced people and maintaining trustworthy professional connections may open doors that would otherwise remain unnoticed. Protect time for health, family, meaningful relationships, and learning from people whose experience can help you grow.
The Reality Behind the Same 24 Hours. The statement that everyone has 24 hours in a day is true, but the opportunities available within those hours are not equal. A person managing two jobs, caring for family members, travelling long distances, or dealing with financial insecurity may have far less discretionary time than someone with greater resources. Financial hardship can also force people to prioritise urgent needs over long-term plans. This is why wealth should never be treated as proof of superior character, nor poverty as proof of poor discipline. The lesson is that habits matter, but circumstances matter too. We should focus on improving the choices within our control while recognising the barriers that may require additional resources, support, or opportunity to overcome.
Five Small Habits That Can Improve Your Financial Future: You do not need to transform your entire life overnight. Begin with a few practical actions:
i) Track your spending.
ii) Learn consistently.
iii)Save regularly.
iv)Review your goals.
v) Make deliberate choices.
Repeat these actions until they become familiar routines. Review what is working and change what is not.
Conclusion: Your Future Is Influenced by What You Repeat.
You cannot control every economic condition, predict every setback, or guarantee wealth through discipline alone. But you can learn to manage money more deliberately, improve your skills, prepare for risks, and make better use of the opportunities available to you.
Do not measure success only by how much you earn today. Measure it also by the financial security, knowledge, choices, and freedom you are building for tomorrow. You have 24 hours today. Use a portion of them to build a better foundation for the life you want.
Admin, Wealthio